For decades one rule defined Cyprus bookkeeping: every company, however small, needed a full statutory audit. In 2026 that finally softened — and a few myths that still circulate (yes, including the “€350 levy”) deserve burying. If you run a Cyprus company, this is what the accounting and audit year actually looks like now: what you must prepare, the new review option for small companies, the filings and deadlines, and where banking still fits in.
The Audit Rule and the 2026 Softening
Start with the baseline, because it is stricter than most EU peers. Under the Companies Law (Cap. 113), every Cyprus private company has historically needed its annual financial statements audited by a licensed statutory auditor — no small-company exemption, unlike much of the EU. That is why “cheap Cyprus company” was always a slight misnomer once you added the mandatory audit.
2026 brings the first real relief. For financial years beginning on or after 6 February 2026, a small company can replace the full statutory audit with a lighter review engagement under ISRE 2400 — provided it stays under the thresholds. It is not a full exemption, you still get an assurance report, but it is a genuine cost reduction for the smallest companies, the first in living memory. Check here for the current accounting rules for Cyprus company.
Who Qualifies for the Review Instead of a Full Audit
The thresholds are tight, so check them carefully before assuming you qualify. The review option applies to a company whose net turnover is below €300,000 and whose total gross assets are below €500,000, with both conditions met for two consecutive years. Cross either ceiling, or fail the two-year test, and you are back to a full statutory audit.
For a genuinely small holding company or a lean consulting vehicle, this can meaningfully cut the annual bill. But note what did *not* change: Cyprus still requires IFRS-compliant financial statements and does not permit the abbreviated or “filleted” accounts many other EU states allow for small companies. So even a review-eligible company prepares full IFRS accounts; only the assurance layer on top gets lighter.
The Filings, Deadlines, and the Levy Myth
Here is the calendar that actually keeps a Cyprus company compliant. You prepare annual financial statements, have them audited (or reviewed, if eligible), file a corporate income tax return with the Tax Department, and file the annual return (form HE32) with the Registrar of Companies together with the financial statements. Provisional tax is paid during the year in two instalments, with a final balancing payment after year-end.
And now the myth worth killing: the €350 annual company levy was abolished in 2024 and no longer exists — yet it still appears on outdated checklists and in nervous WhatsApp messages. If a provider is still charging or citing it, that is a red flag about how current their information is. What remains is real work — audited/reviewed IFRS accounts and timely filings — not a flat annual levy.
Where Banking Fits — and Why Clean Accounts Help
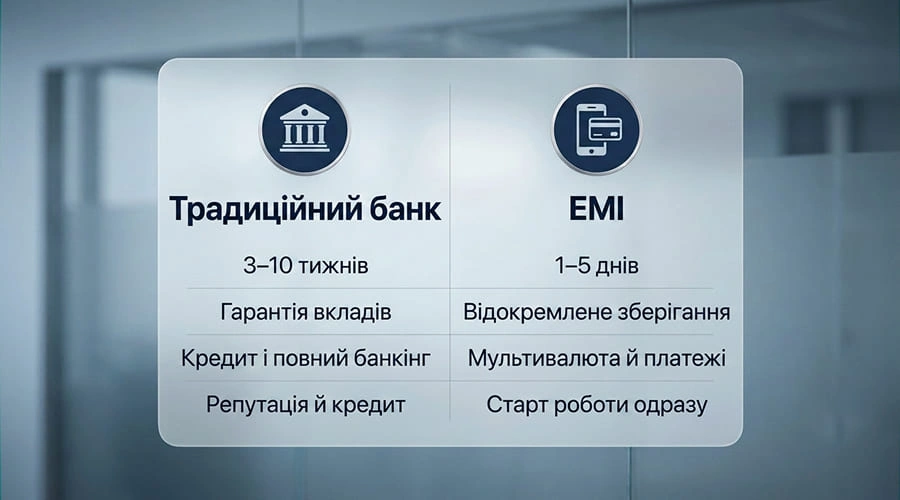
Accounting and banking are more connected in Cyprus than founders expect. Opening a corporate bank account in Cyprus takes roughly 3–5 weeks for EU-resident beneficial owners and 6–10 weeks for non-EU or complex structures, and banks increasingly want to see that a company is a real, well-kept entity — recent audited accounts, a coherent activity, clean UBO records.
That makes good bookkeeping a banking asset, not just a tax chore. A company with current, audited (or reviewed) financials and a clear picture of its activity onboards and passes ongoing reviews far more smoothly than one scrambling to reconstruct its accounts when the bank asks. Keep the books current through the year, and both the tax deadlines and the banking relationship take care of themselves.
FAQ
Does every Cyprus company still need an audit in 2026?
Not necessarily. The full statutory audit remains the default under Cap. 113, but for financial years beginning on or after 6 February 2026, small companies below the thresholds can use an ISRE 2400 review engagement instead.
What are the thresholds for the review option?
Net turnover below €300,000 and total gross assets below €500,000, with both conditions met for two consecutive years. Exceed either, and a full audit is required.
Is the €350 annual company levy still payable?
No. The annual company levy was abolished in 2024. If a checklist or provider still lists it, their information is out of date.
Can a small Cyprus company file abbreviated accounts?
No. Cyprus requires full IFRS-compliant financial statements and does not permit abbreviated or “filleted” accounts, regardless of company size. The 2026 change is to the assurance level, not the accounts themselves.
How long does it take to open a Cyprus bank account?
Around 3–5 weeks for EU-resident UBOs and 6–10 weeks for non-EU or complex structures. Recent, well-kept accounts and clean UBO records make onboarding and ongoing reviews smoother.
Conclusion
Cyprus accounting in 2026 is genuinely lighter at the small end than it has ever been — the ISRE 2400 review option finally spares the smallest companies a full audit for financial years starting from 6 February 2026 — while the scary-sounding €350 levy is simply gone. What remains is disciplined and worthwhile: full IFRS accounts, an audit or review, timely tax and Registrar filings, and books kept current enough to satisfy a bank. Get the assurance level right for your size, drop the outdated worries, and Cyprus stays as efficient to run as it is to set up.
Not sure whether your Cyprus company qualifies for the new review option — or scrambling to get the accounts and filings current? Send us your turnover, assets and year-end on Telegram or WhatsApp, and we will confirm your audit position and handle the bookkeeping, assurance and filings end to end.
Дізнайтеся, як захистити свій бізнес.
Отримайте цінні юридичні консультації для вашого стартапу або ІТ-проєкту, щоб уникнути ризиків і зосередитися на зростанні.
Ця стаття має виключно інформаційний характер і не є юридичною, податковою чи фінансовою консультацією. Перед прийняттям рішень зверніться до кваліфікованого фахівця. Редакційна політика.